Calculator · Vaping Products Duty
Vape duty calculator UK: duty and VAT per unit, pack and case
On this page10 sections
Short answer: UK Vaping Products Duty is £2.20 per 10ml of liquid (22p per ml), nicotine or not. Multiply the ml by 22p and round down to the penny. VAT at 20% is charged on the price including the duty, so every 10ml adds £2.64 to a consumer price. The calculator below works it out per unit, per retail pack and per case, using HMRC's own method.
Work out the duty on one product line
Enter one line at a time. Use the volume printed on the retail pack; if your supplier's invoice or delivery note shows a bigger figure, use that (see why below).
| Per | Duty |
|---|---|
| Enter the ml per unit to see the duty. | |
The first question we'd ask you: does your price list show duty on its own line, or is it folded into the trade price? Your figures go into the message for you. Add your name and email; nothing is sent until you press send.
The calculator runs in your browser and uses only the £2.20 per 10ml rate and the 20% VAT rate. Nothing you type is sent anywhere unless you choose to send it.
How HMRC works out the duty
HMRC's internal manual for Vaping Products Duty (section VPDS101900) sets out the method: the £2.20 rate is per 10ml, so it's 22p per ml, multiplied by the volume, and the result is rounded down to the nearest penny. Its own worked examples:
| Example in HMRC's manual | Volume | Duty |
|---|---|---|
| A vape device containing 2ml | 2ml | 44p |
| A total of 3 litres of vaping product | 3,000ml | £660.00 |
| A seized batch of 45,000 pods of 2ml each | 90,000ml | £19,800.00 |
Two things follow for anyone pricing stock. First, the rate doesn't change with nicotine strength, flavour or price, so cheap high-volume lines carry the most duty relative to their price. Second, the round-down only matters on odd volumes. Any whole number of millilitres comes out to an exact penny amount, but a 1.8ml pod is £0.396 of duty, which rounds down to 39p.
Per pack or per case: where the pennies go
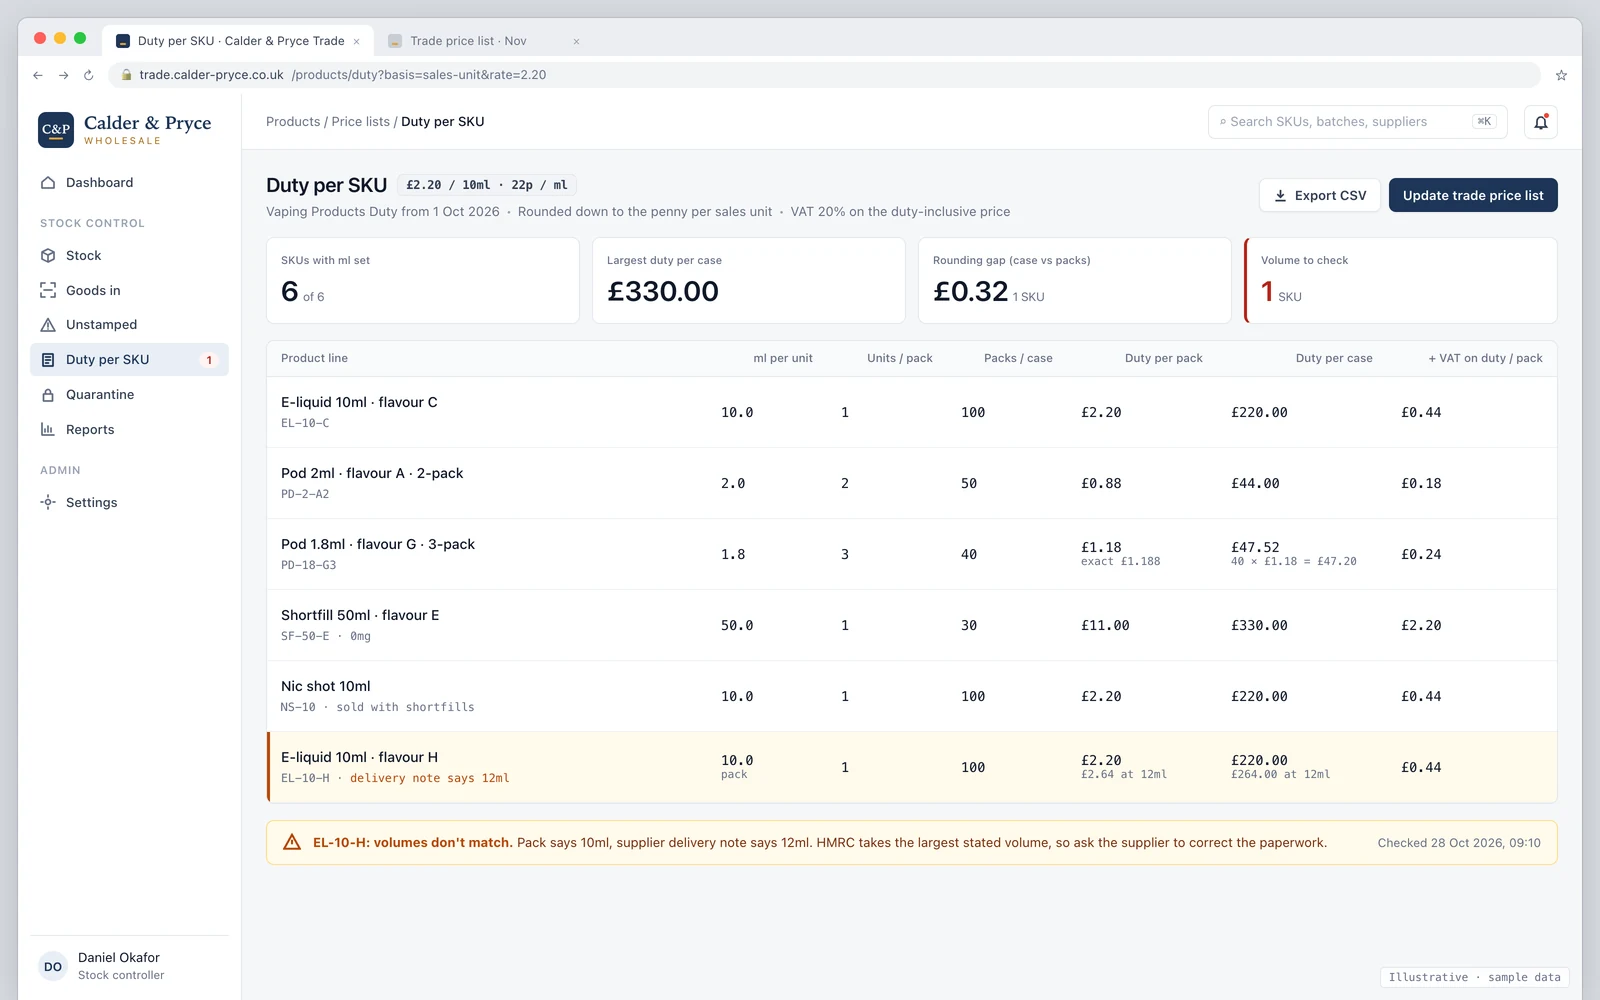
Rounding down at different levels gives different totals. Take a 3-pack of 1.8ml pods sold in cases of 40:
| Basis | Sum | Duty |
|---|---|---|
| Rounded per pod, then multiplied | 39p × 3 × 40 | £46.80 |
| Rounded per pack (5.4ml), then multiplied | £1.18 × 40 | £47.20 |
| Worked out on the case (216ml) | 216 × 22p | £47.52 |
Only the business that accounts for the duty, usually the manufacturer, importer or warehouse, declares it to HMRC. For a wholesaler the duty is part of the buy price, and the question is which figure you print on price lists and invoices. Our advice: work it out per sales unit (the pack you actually invoice), state that basis on your price list, and keep it the same everywhere so a customer comparing a pack price with a case price doesn't find pennies that don't add up.
Which volume counts
HMRC's manual (VPDS102000) says the volume of a prefilled container is taken from any of these:
- the actual volume the container is filled with
- the volume stated on the retail packaging
- the volume stated on an invoice
- the volume stated on a delivery note, or a similar document
Where they differ, the largest one is used, unless it's an obvious error such as an invoice showing 10 litres for one 10ml bottle. Volumes under 1 litre are measured to the nearest 0.1ml and larger volumes to the nearest 1ml, at 18°C to 22°C.
For a wholesaler, that makes the supplier's paperwork part of the duty sum. If a delivery note says 12ml for a 10ml bottle, the duty basis for that line is £2.64, not £2.20. Ask the supplier to correct the document, and keep the ml figure on your own product record to one decimal place so you can spot the mismatch at goods-in.
VAT on top of the duty
HMRC's VAT guide (Notice 700, section 7.7) says that for goods subject to excise duty, the value for VAT is the price plus the duty. So the 20% VAT is worked out on the duty-inclusive price:
VAT-inclusive price = (your price + duty) × 1.2
For a VAT-registered shop buying from you, the VAT is normally reclaimable, so the cost that sticks is the duty. For the vaper at the till, every 10ml carries £2.20 of duty and 44p of VAT on that duty.
What counts as liquid for the duty
HMRC's manual (VPDS031000 and VPDS032000) makes three points that catch people out:
- Nicotine isn't the test. A liquid doesn't have to contain nicotine to be liable, so 0mg shortfills pay the same rate per ml as nicotine e-liquid.
- Mix-it-yourself liquids still count. A liquid is a vaping product even if it has to be mixed with another liquid first. HMRC's example is adding a nic shot to a shortfill, so a 50ml shortfill sold with a 10ml nic shot carries 60ml of duty: £13.20.
- It's the liquid, not the hardware. The duty is on the vaping liquid. Empty devices, batteries and chargers carry no Vaping Products Duty.
Who pays it, and when
Duty is due when vaping products are released for consumption in the UK: when they leave duty suspension, or when they're imported if they don't go into a duty suspension arrangement (VPDS101300). That's the UK manufacturer, the importer or the excise warehouse. A wholesaler that only buys and sells duty-paid stock doesn't pay duty to HMRC directly and doesn't need approval; it pays the duty inside its buy price. HMRC's own announcement says whether the duty is passed along the supply chain is a commercial decision.
The rest of the duty picture is in our other guides: the Vaping Products Duty guide for wholesalers covers approval, dates and records, the duty stamp goods-in checklist covers stamps, and the unstamped stock calculator shows which old lines won't clear by 31 March 2027.
Price-list checks before your next update
| Check | Why it matters |
|---|---|
| Every SKU has liquid volume in ml, to 0.1ml | Duty can't be calculated without it, and HMRC measures to 0.1ml |
| Pack size and case size are separate fields | Duty per pack and per case come from different volumes |
| One rounding basis, written on the price list | Avoids pack and case prices that don't reconcile |
| Duty shown as its own line, before VAT | Customers can see what's duty and what's your margin |
| Supplier volume on invoices matches the pack | HMRC uses the largest stated volume |
| Nic shots and shortfills priced as separate liquids | Both carry duty |
How we help
We build trade ordering portals for UK vape wholesalers, and we set up the product data behind this calculator: ml per unit, pack and case sizes, duty worked out per sales unit and shown as its own line on price lists and invoices, and a goods-in check that flags a supplier volume that doesn't match the pack. Our trade portal already runs sales and warehousing day to day for a UK vape wholesaler; duty lines like these are set up as part of a project. You get a fixed quote after a 20-minute walkthrough. Book a walkthrough, send us your price list questions, or see our vape wholesale software and B2B ordering portal pages.
Sources
- HMRC internal manual, VPDS101900: Calculating duty (rate per ml, worked examples, round down to the nearest penny)
- HMRC internal manual, VPDS102000: Measuring volume for duty calculations
- HMRC internal manual, VPDS031000: Legal definition and VPDS032000: Constituent parts
- HMRC internal manual, VPDS101300: Duty point
- HMRC, Introduction of Vaping Products Duty from 1 October 2026 (policy paper, 26 November 2025: £2.20 per 10ml regardless of nicotine)
- HMRC, Handling wholesale or retail vaping products in the UK (updated 7 October 2026: no approval needed to only sell duty-paid products)
- HMRC, One month until Vaping Products Duty and the Vaping Duty Stamps Scheme start (1 September 2026: "a commercial decision")
- HMRC, VAT guide (VAT Notice 700) (updated 25 June 2026; section 7.7, excise duty in the value for VAT)
Last reviewed 28 October 2026. This calculator applies HMRC's published rate and method. It isn't legal or tax advice; if you manufacture, import or hold goods in duty suspension, read HMRC's full guidance or ask a customs adviser.