Guide + calculator · Unstamped stock
Unstamped vape stock: will you clear it by 31 March 2027?
On this page6 sections
Short answer: you can keep selling unstamped vaping products until 31 March 2027, but only stock that was produced in or imported into the UK before 1 October 2026, and only if you can show that. From 1 April 2027 you must not hold or sell any of it. The calculator below tells you, line by line, whether you'll sell through in time at your current rate.
From our side
Honestly, the calculator is the easy bit. The hard bit is knowing your real weekly sales per SKU. A lot of wholesalers only know it roughly, which is why we pull it straight from the order history in the portal.
— Avi Singh, Founder
Check each line
Enter figures for one SKU at a time. Use your average weekly sales over the last 8–12 weeks, not your best week.
The calculator runs in your browser. Nothing you type is sent anywhere.
What the result means
- Clears with weeks to spare: keep going, but review it monthly. Sales often drop after a price rise, and October's duty adds £2.20 per 10ml to new stock, which changes what customers buy.
- Won't clear: act now while you have options. In February you'll have far fewer.
The options for stock that won't sell in time, in the order most wholesalers try them:
- Sell it faster to the trade. Bulk and trade discounts are still allowed after 29 October 2026. A clearance price list for your trade customers is normal business.
- Return it to the supplier. Easier in November than in March, when every wholesaler is asking.
- Export it, where the product can be legally sold in the destination market.
- Destroy it lawfully and keep the evidence. Single-use devices have their own recycling rules, which you'll already be following if you cleared stock after the June 2025 ban.
What HMRC actually says about leftover stock
HMRC's page for wholesalers and retailers (updated 7 October 2026) words this in two places. Under "From 1 April 2027" it says: "You should make sure that any unstamped stock has been sold, returned to your supplier, or otherwise lawfully dealt with before this date." Under "Selling existing unstamped stock" it says: "By 1 April 2027, you should make sure any unstamped stock has been sold, returned to your supplier, exported, destroyed, or otherwise lawfully dealt with." Options 3 and 4 above come from that second list. Whichever you use, HMRC says that after 1 April 2027 it may seize goods, charge penalties and, in the most serious cases, investigate criminally.
HMRC also says: "If you cannot satisfy yourself that the stock is legitimate, you should not buy, supply or sell it." So don't top up an unstamped line from a supplier after 1 October 2026 unless they can show it was produced or imported before that date, with normal invoices and delivery notes.
Be careful with consumer promotions. From 29 October 2026 it's an offence to sell vaping products at a substantial discount, or give them away, where the purpose or effect is to promote them. DHSC's guidance says normal discounting and clearing unsold stock at a reduced price are still fine.
Keep the evidence while you sell through
During the grace period your records have to explain why a product is unstamped. For every unstamped line keep:
- the supplier invoice and delivery note, with dates before 1 October 2026
- batch or production details where you have them
- the goods-in check you did and who did it
- what you did with any stock that didn't sell (sold, returned, exported, destroyed), when, and the paperwork for it. HMRC's own list asks for "what action you took if products were unstamped, unclear or appeared non-compliant".
Keep all of it for at least six years. HMRC's record-keeping guidance says electronic records must be exportable in a readable format on request.
Making this automatic
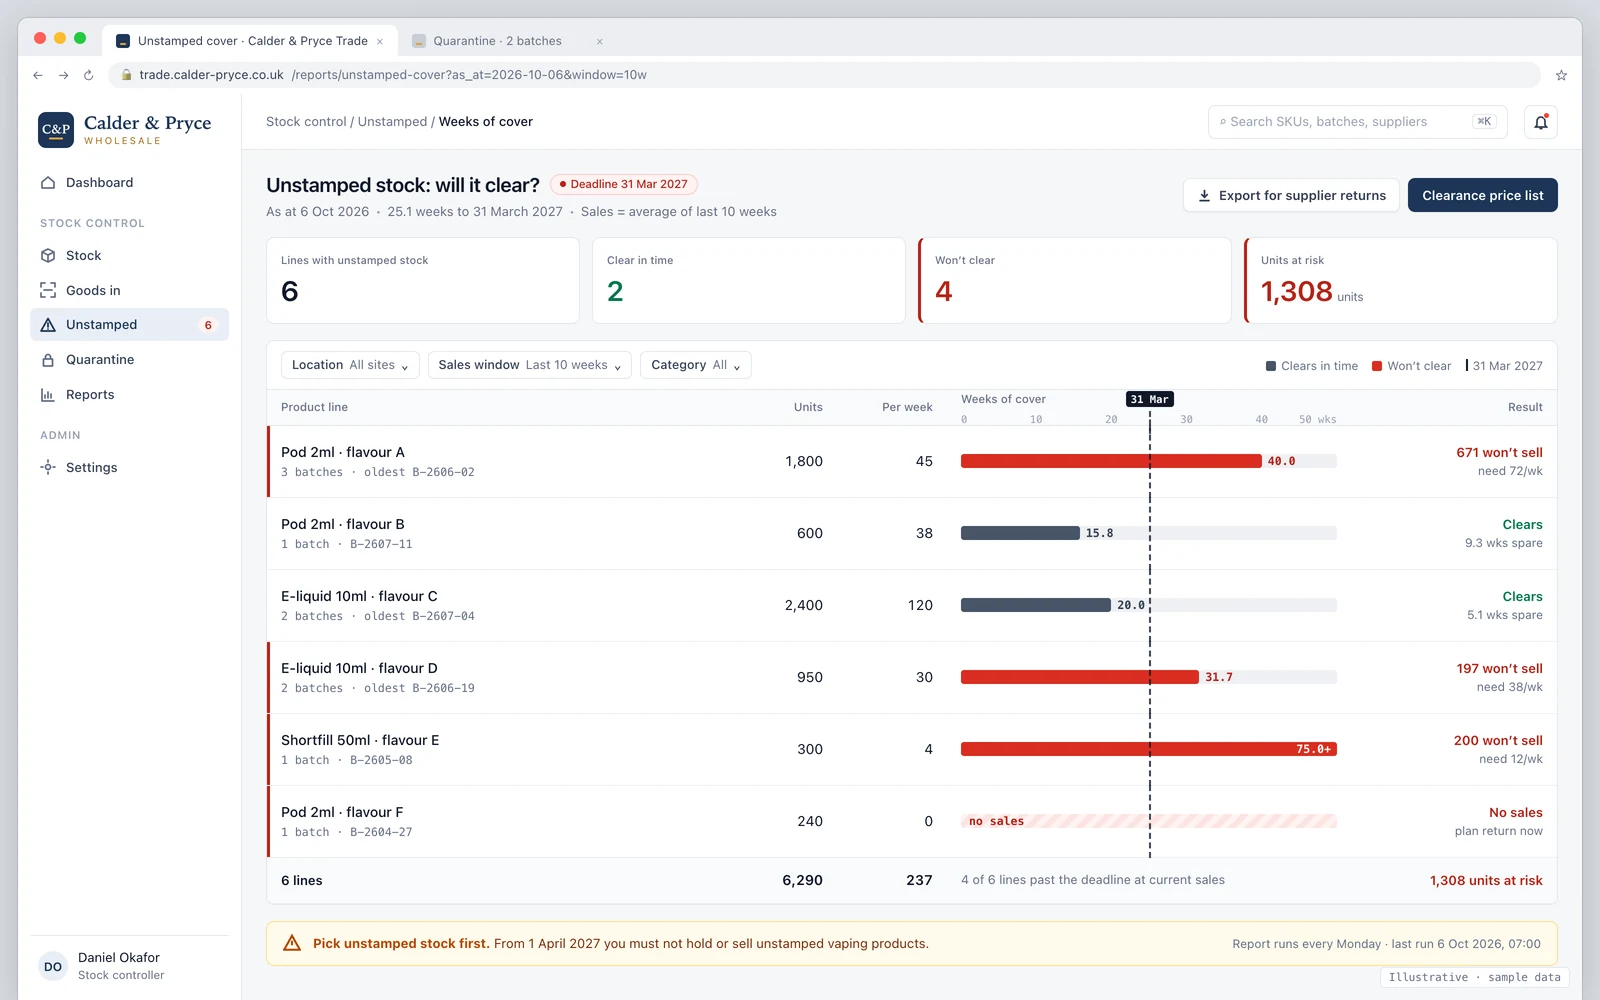
Doing this check once in a spreadsheet is fine. Doing it every week for hundreds of SKUs is where it breaks. The trade portals we build do it for you: a weekly weeks-of-cover report on every unstamped SKU, unstamped stock picked first, and a hard block on unstamped sales from 1 April 2027. See how it works in a 20-minute walkthrough, or read the full Vaping Products Duty guide for wholesalers and the duty stamp goods-in checklist.
Sources
- HMRC, Handling wholesale or retail vaping products in the UK (updated 7 October 2026; re-checked 28 October 2026)
- HMRC, Keeping records for Vaping Products Duty and the Vaping Duty Stamps Scheme (published 1 April 2026; no later updates on 28 October 2026)
- DHSC, Selling vaping and nicotine products (published 11 August 2026)
- DEFRA, Single-use vapes ban
Last reviewed 29 October 2026. This guide explains published government guidance and isn't legal or tax advice.