Guide · UAE e-invoicing
ERP integration for UAE e-invoicing: what your system must do before go-live
On this page14 sections
Short answer: UAE e-invoicing is live for early adopters, and it becomes mandatory from 1 January 2027 for businesses with revenue of AED 50 million or more. Their deadline to appoint an Accredited Service Provider (ASP) was 30 October 2026, and it has now passed: if you are in that group and haven't appointed one, do it now, because go-live is unchanged. Everyone else appoints by 31 March 2027 and goes live on 1 July 2027. The ASP carries invoices across the Peppol network and reports to the FTA, but your ERP, billing app or portal still has to produce all 51 mandatory fields, correctly, for every invoice and credit note. That ERP integration is the part most businesses underestimate.
From our side
Every UAE client asks "which ASP should we pick?" first. Wrong first question. The ASP only carries the invoice. If your system can't produce the 51 fields cleanly, no ASP fixes that. Start with one real invoice and see which fields are missing.
— Avi Singh, Founder
This guide is for the people who look after the system that raises invoices: finance managers, IT leads and owners of businesses running custom, in-house or portal-based billing. It covers the dates, who is in scope, what the ASP does and what stays with you, how to map the 51 fields, and the questions to ask before you sign with an ASP.
Status today, 9 November 2026
We re-opened the Ministry of Finance (MoF) and Federal Tax Authority (FTA) pages on 9 November 2026 and checked every statement on this page against them.
| Question | What the official sources say today |
|---|---|
| Has the 30 October 2026 appointment date for businesses with revenue of AED 50 million or more moved again? | We found no change and no later extension. The FTA's notice of 25 October 2026 repeats 30 October 2026 to appoint an ASP and 1 January 2027 to implement. The MoF hub shows no newer decision |
| What if we missed it? | Cabinet Decision No. 173 of 2026 sets the penalty for not appointing an ASP: AED 5,000, then AED 5,000 for each month or part month, capped at AED 50,000 in 12 consecutive months. We found no announced grace period. Go-live stays 1 January 2027 |
| Which MoF documents are current? | Guidelines v2.0 (26 October 2026), Mandatory Fields v1.1 (28 October 2026) and Considerations for selecting an ASP v1.1 (28 October 2026). The old Guidelines v1.1 address now redirects to v2.0 |
| How many ASPs are there? | The MoF's list showed 86 Accredited Service Providers on 9 November 2026. On 6 October it showed 64 fully accredited and 2 in final assessment |
| Format version | OpenPeppol's PINT AE specification is still version 1.0.4 (29 July 2026) |
Timeline: the dates that apply to you
Your phase depends on revenue, defined in Ministerial Decision No. 244 of 2025 as gross income in the financial statements for your most recent accounting period (or other documentation the FTA accepts if you have no statements). The decision says "equal to or exceeds" AED 50 million, so a business at exactly AED 50 million is in the first phase.
| Who | Appoint an ASP by | Mandatory go-live | Notes |
|---|---|---|---|
| Pilot group (MoF Taxpayer Working Group) | By invitation | From 1 July 2026 | Written consent only |
| Any business, voluntarily | When you choose | From 1 July 2026 | Full technical rules apply; the penalty decisions don't |
| Revenue AED 50m or more | 30 October 2026 | 1 January 2027 | Moved from 31 July 2026 by Ministerial Decision No. 66 of 2026 |
| Revenue below AED 50m | 31 March 2027 | 1 July 2027 | |
| Government entities | 31 March 2027 | 1 October 2027 | |
| Transactions between members of one tax group | — | Excluded for 24 months from 1 January 2027 | Added by Ministerial Decision No. 197 of 2026 |
| Air cargo under an air waybill | — | Excluded for 24 months from the date the system becomes effective | Ministerial Decision No. 243 of 2025, Article 4 |
Only the first-phase appointment date has moved. Ministerial Decision No. 66 of 2026 changed it from 31 July to 30 October 2026. The Ministry of Finance described the amendments as targeted and said the 1 January 2027 go-live stays unchanged, and the FTA's 25 October notice repeats 30 October. One mismatch to know about: the phase table in the Guidelines v2.0 prints 31 October 2026 as the last date to appoint an ASP, a day later than the decision and the FTA. Plan on the decision's 30 October; either date has now passed. Some third-party guides still show the old 31 July date.
Who is in scope
E-invoicing is not only for VAT registrants. Ministerial Decision No. 243 of 2025 covers every business transaction by any person doing business in the UAE, covering B2B, B2G, G2B and G2G.
| Your situation | In scope? | What it means |
|---|---|---|
| VAT-registered, selling to businesses | Yes | Tax invoices and tax credit notes become e-invoices and e-credit notes |
| Not VAT-registered, selling to businesses or government | Yes | You issue commercial e-invoices; register with the FTA for a TIN if you have no tax registration |
| Selling only to consumers (B2C) | No | Out of scope until the Minister decides otherwise |
| Selling to both businesses and consumers | Yes, for business sales | Consumer sales stay outside e-invoicing |
| Non-resident that must issue UAE tax invoices | Yes | Those invoices are issued as e-invoices |
| Holding company with only passive income | No | A recharge, such as a management fee, brings it in |
| Imports under the reverse charge | No e-invoice needed | Domestic reverse-charge supplies still need an e-invoice without VAT |
| Your customers haven't onboarded yet | Yes | A customer's e-invoicing or tax registration status doesn't change your obligation. A buyer who isn't on the system may still want a separate PDF tax invoice (see the pitfalls below) |
| Excluded supplies | No | Government sovereign activity not in competition with the private sector; international passenger air transport where an e-ticket is issued, and ancillary services with an electronic miscellaneous document; VAT-exempt financial services, including exempt services to non-residents that qualify as zero-rated exports (financial services that are standard-rated to residents are not excluded); and, for 24 months from 1 January 2027, transactions between members of the same tax group |
How the exchange works
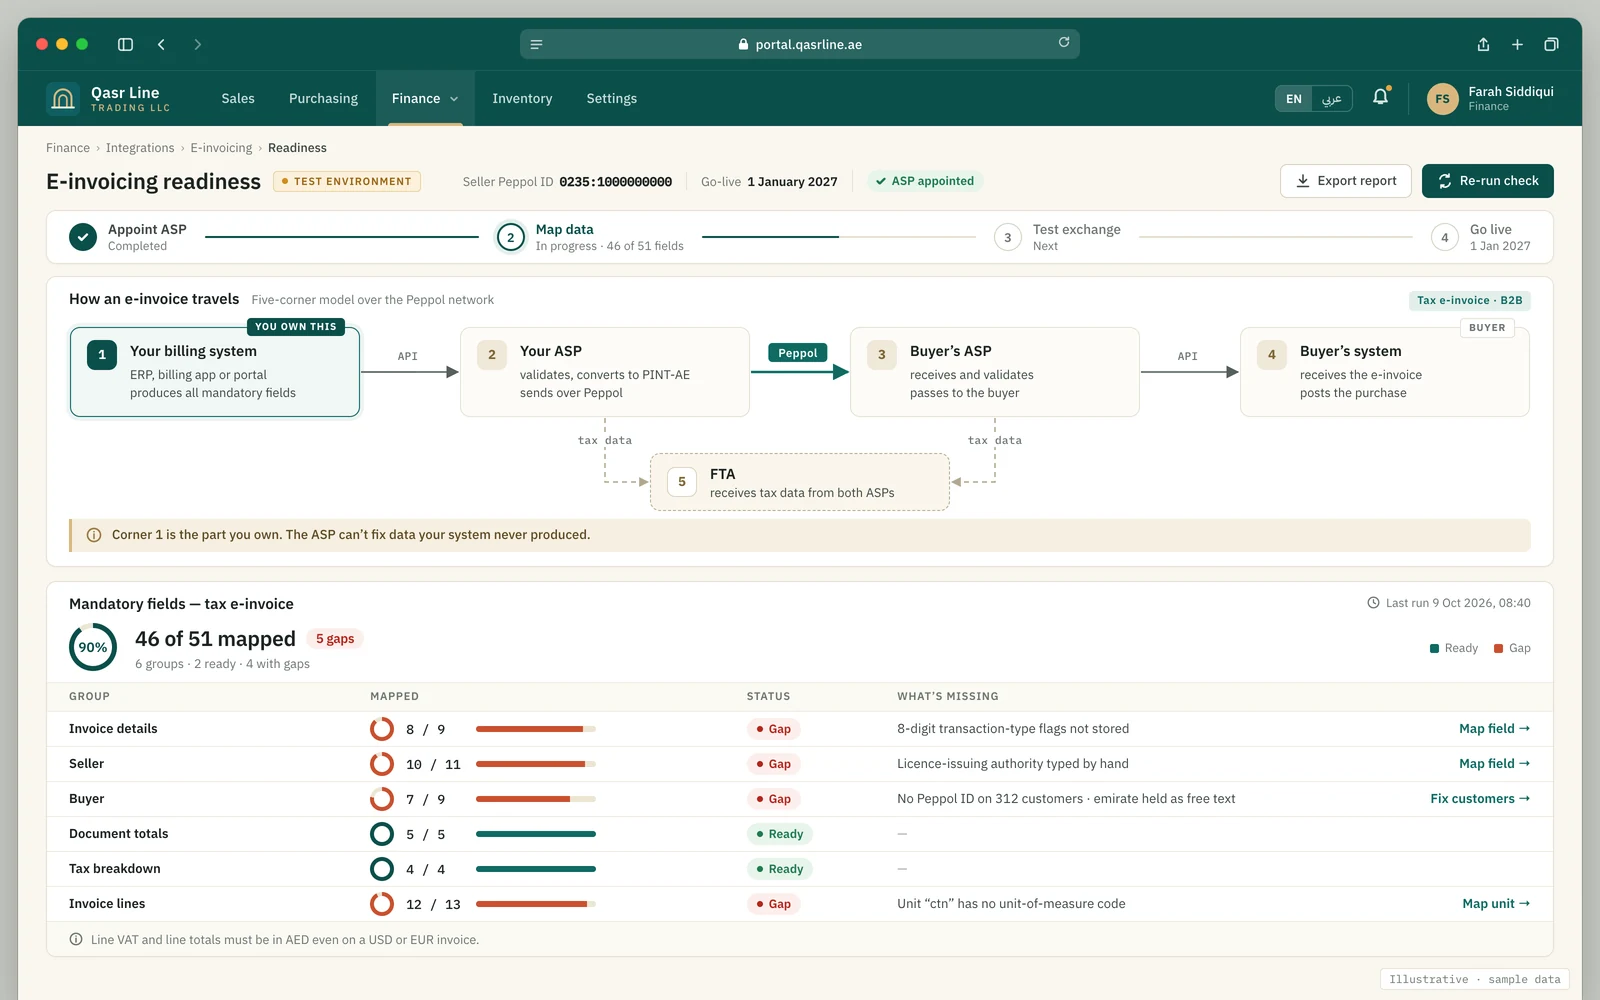
The UAE uses a Peppol "five-corner" model. Your system (corner 1) sends invoice data to your ASP (corner 2). The ASP validates it, converts it to PINT-AE XML and delivers it to the buyer's ASP (corner 3), which passes it to the buyer (corner 4). Both ASPs report the tax data to the FTA (corner 5), and confirmations flow back. The e-invoice has no QR code or barcode, and the format supports Arabic and English.
Saudi Arabia works differently: there, your own invoicing system connects straight to ZATCA's Fatoora platform, with no accredited service provider in between. If you also invoice in Saudi Arabia, see ZATCA Phase 2 integration for custom ERPs. In Malaysia, your system can submit to LHDN's MyInvois API directly or through an intermediary; see MyInvois integration for your own ERP or billing system.
Your address on the network is 0235: plus your 10-digit Tax Identification Number (TIN), the first
10 digits of your 15-digit TRN; your ASP registers it for you when you onboard. You start onboarding yourself, from the e-invoicing tile in the FTA's
EmaraTax portal, after signing with an ASP. Each business uses one ASP for both sending and
receiving, and each member of a tax group onboards under its own TIN and may choose a different ASP.
What an ASP does and what your own system must do
The MoF's e-invoicing guidelines v2.0, section 5.2 are clear that the ASP carries the invoice but the compliance obligation stays with the supplier.
| Task | ASP | Your ERP, billing app or portal |
|---|---|---|
| Hold correct customer and product data | No | Yes: buyer TRN/TIN, Peppol ID, address, emirate, unit codes, tax categories |
| Calculate every invoice value, including AED amounts | No | Yes |
| Produce the data for all mandatory fields | Receives it | Yes, in a format the ASP accepts |
| Gather the buyer's Peppol participant ID | No | Yes, from the customer |
| Look up the buyer on Peppol and transmit securely | Yes | No |
| Assign a unique identifier (UUID) to each e-invoice | Yes | Keep your own unique invoice numbers |
| Validate, convert to PINT-AE XML and report to the FTA | Yes | No |
| Return confirmations and rejections | Yes | Store them, show them to staff, fix and resend |
| Issue and transmit within 14 business days of the earlier of the transaction or the payment (VAT-registered issuers must also meet the VAT Law timeline) | No | Yes |
| Tell the ASP in writing, within 5 business days of the FTA confirming a change to your registered data | No | Yes |
| Keep records for the retention period | May store them for you if the contract says so | Yes: the legal duty stays with you, and records must be producible on request |
The 51 mandatory fields: a mapping exercise
The MoF's mandatory fields list (v1.1, 28 October 2026) sets 51 fields for a tax e-invoice and 49 for a commercial e-invoice. Most exist somewhere in your database already. The work is finding where, filling the gaps and agreeing a rule for each one. For the codes themselves (Peppol ID, transaction flags, emirate and unit codes) see our UAE e-invoice format guide.
| Group | Fields | Where it usually lives | Typical gap |
|---|---|---|---|
| Invoice details | 9: number, date, type code, currency, transaction-type flags, payment due date, business process type, specification ID, payment means | Invoice header, order, payment terms | The 8-digit flag string (free zone, deemed supply, margin scheme, summary, continuous supply, disclosed agent, e-commerce, exports) isn't recorded anywhere |
| Seller | 11: name, electronic address (TIN), identifier 0235, legal registration ID and type (TL, EID, PAS or CD), tax identifier (TRN, or the 10-digit TIN if not VAT-registered), tax scheme, address, city, emirate, country |
Company settings | The licence-issuing authority is typed by hand, with no code list |
| Buyer | 9: name, electronic address, identifier, TRN, tax scheme, address, city, emirate, country | Customer master | TIN or Peppol ID never collected; emirate held as free text |
| Document totals | 5: line net total, total without tax, total tax, total with tax, amount due | Invoice totals | Totals that don't match the lines after rounding |
| Tax breakdown | 4: taxable amount, tax amount, category code and rate per category | Tax settings | Local tax codes that don't map to standard, zero-rated, exempt, out of scope, reverse charge or margin scheme |
| Invoice lines | 13: line ID, quantity, unit-of-measure code, net amount, net and gross price, price base quantity, tax category and rate, VAT in AED, line amount in AED, item name and description | Order lines, item master | Unit labels such as "ctn" instead of a unit-of-measure code (the MoF's example is KG); no AED amounts on USD or EUR invoices |
A commercial e-invoice drops the two AED line fields and swaps the buyer's tax identifier and tax scheme for the buyer's legal registration ID and type, which is how it reaches 49.
Four rules catch people out. Line VAT and line totals must be in AED even when you invoice in another currency, converted at the Central Bank rate, and the tax accounting currency field becomes mandatory. You can't add your own optional fields to PINT-AE, so anything your customers rely on has to fit the fields that exist. And there is no "provisional invoice" category: a provisional invoice is an e-invoice, adjusted later by a credit note or a further invoice. Finally, HS/HSN item codes are optional for now; the Ministry says it will announce when they become mandatory.
IT readiness checklist
Work through this with whoever owns your billing system. The MoF publishes its own e-invoicing hub and checklists; this list is the system side of it.
- Confirm your phase from the revenue in your most recent financial statements, and put the appointment and go-live dates in the project plan.
- Check your own registration. Trade licence, address and TRN in EmaraTax must be current. Without any tax registration, apply for a TIN first.
- Clean the customer master. For every business and government customer: legal name, TRN or TIN, Peppol participant ID, address, city and emirate. Ask customers for their Peppol ID now.
- Clean the product master. Item names and descriptions, a proper unit-of-measure code, and a tax category on every item.
- Fix invoice numbering. Unique, never reused, with cancelled invoices reversed by credit note rather than deleted.
- Make credit notes first-class documents. E-credit notes are needed for cancellations, price reductions, returns and errors, and they should reference the original invoice (one credit note can reference several invoices, and a partial credit note is allowed).
- Store AED amounts for every line on foreign-currency invoices, with the rate used.
- Record scenario data: free-zone beneficiary details where the end user differs from the buyer, export and deemed-supply flags, summary or continuous-supply invoices, and advance payments (a tax e-invoice is issued when the advance is received, and the final invoice covers only the balance and references it).
- Do the mapping sheet. One row per mandatory field: source table and column, transformation, default, and who fixes gaps.
- Build the connection to your ASP (API, file exchange or ERP connector) and bring confirmations and rejections back into your system with an error queue your team works daily.
- Watch the 14-day clock. Alert staff when an invoice hasn't been accepted within a few days.
- Test end to end with the ASP before go-live: sending, receiving, FTA reporting, credit notes, foreign currency and every scenario you use.
- Plan the purchase side. Supplier e-invoices will arrive through the same ASP and need matching to purchase orders.
- Set up archiving for e-invoices, credit notes and confirmations for the full retention period.
How to choose an ASP
The official list of accredited and pre-approved ASPs showed 86 Accredited Service Providers on 9 November 2026 (on 6 October it showed 64 fully accredited and 2 in the final production assessment), and it changes often. We don't recommend any particular provider. These questions combine the MoF's considerations for selecting an ASP (v1.1, 28 October 2026) with the checks a custom or in-house system needs:
- API: Is there a documented REST API and a test environment? Can we see the documentation before signing?
- Formats: Will it accept our data as JSON or CSV and build the XML, or must we send PINT-AE XML?
- Feedback: How do confirmations and rejections come back: webhook, polling or email?
- Connectors: Is there a ready connector for our ERP, and who maintains it when the ERP updates? If you run Odoo, SAP Business One or Zoho Books, our guide to UAE e-invoicing in those three ERPs sets out what each vendor provides today.
- Pricing model: Subscription or per invoice? Are receiving, storage and support charged separately? Are the 100 free e-invoice exchange and reporting services a year for each end-user, counted from the date you sign, that ASPs commit to under Ministerial Decision No. 168 of 2026 written into the contract?
- Data and retention: Where is our data stored, how long does the ASP keep our e-invoices, can it store them for us, and can we export all of it if we leave? The legal duty to retain stays with you.
- Track record and security: How long has it been an ASP in the UAE (its accreditation date), which security certifications does it hold, and how does it protect data in transit and at rest?
- Product ownership: Is it the ASP's own platform or a resold one?
- Service levels: What uptime and support response times are promised, and in which hours?
- Scale: Can it handle our peak invoice volume without throttling?
Once you have chosen, run our 12-case ASP test plan before go-live.
Storage and offshore servers
MD 243 originally said records must be stored "within the State". Ministerial Decision No. 197 of 2026, in force from 1 October 2026, removed that requirement. The rule now is to keep all e-invoices, e-credit notes and related data for the Tax Procedures Law period and be able to produce them to the FTA on request, wherever the servers are. Retention follows the Tax Procedures rules (Guidelines v2.0, section 5.4): five years after the tax period for taxable persons, five years from the end of the calendar year for other persons, seven years for real estate, with extra years during audits, disputes or after a voluntary disclosure. Your ASP may store the records for you if the contract says so, but the obligation stays with you, and no particular system layer is required as long as the data stays intact, secure and producible on request. This matters if your ERP runs on a non-UAE cloud or your developers are offshore.
Penalties
Penalties are set by Cabinet Decision No. 173 of 2026, in force since 15 October 2026, which repealed Cabinet Decision No. 106 of 2025. We read the decision and its penalty table on the UAE legislation portal (Arabic). Voluntary adopters are excluded by Article 2 of the decision.
| Failure | Penalty under Cabinet Decision No. 173 of 2026 |
|---|---|
| Not implementing e-invoicing, including not appointing an ASP; or a recipient not meeting its recipient obligations | AED 5,000, then AED 5,000 per month or part month, capped at AED 50,000 in any 12 consecutive months |
| Not issuing and sending an e-invoice through the system | AED 100 per invoice, up to AED 5,000 per calendar month |
| Not issuing and sending an e-credit note through the system | AED 100 per credit note, up to AED 5,000 per calendar month |
| Not telling the ASP about changes to FTA-registered data | AED 250 per day, up to AED 5,000 per calendar month |
The old AED 1,000-a-day penalty for not reporting a system failure is gone. For the full table, what changed from Decision No. 106 and an exposure calculator, see our guide to UAE e-invoicing penalties.
Common integration pitfalls
- Expecting the ASP to fix your data. It validates and rejects. It can't invent a buyer's TIN or an emirate you never stored.
- Mapping only the standard invoice. Credit notes, foreign-currency invoices, free-zone sales, exports and summary invoices each need testing.
- Rounding. The Guidelines (v2.0, section 12.2) say rounding applies only to the invoice total, to 2 decimal places, not per line or per tax category. Make your logic match and test it against the ASP's validation before go-live.
- Dropping the PDF too early. While a buyer hasn't implemented e-invoicing, you still send a
regular tax invoice (for example a PDF) as well as the e-invoice, and you put the predefined
endpoint
0235:9900000098on the e-invoice. The same endpoint goes on invoices to a foreign buyer who isn't subject to UAE e-invoicing.0235:9900000099is only for an export, flagged as one, to a receiver not on Peppol, and deemed supplies use0235:9900000097. The Guidelines say these endpoints go with the transaction type and the buyer's status, so don't set them on their own. - Hand-typed fields. The licence authority name has no code list, so agree one spelling per authority and store it.
- Tax-group IDs. Each member's TIN comes from its own TRN, not the group representative's.
- Forgetting the purchase side. Supplier e-invoices arrive through your ASP too.
- Starting late. Integration and testing take time, and missing your mandatory date is penalised.
How we help
We're a software company, and we work with UAE businesses remotely. We have no UAE office or licence, and we are not an Accredited Service Provider, can't become one and aren't partnered with any ASP. What we do is build: we change your billing system, ERP or ordering portal so it holds the right master data and produces all the mandatory fields, then connect it to the ASP you choose through that ASP's API, with confirmations, rejections and an error queue brought back into your system. If your system can't be changed, we can build the layer that sits between it and the ASP.
You get a fixed quote after a 20-minute call, so the full cost is known before work starts. Book a call or ask for a price. For the invoice rules themselves, read our guide to UAE tax invoice requirements, or see what we build for UAE businesses.
Sources
- Ministry of Finance, eInvoicing programme hub (accessed 9 November 2026)
- Ministry of Finance, UAE eInvoicing Programme briefing (October 2026): legislation list showing Cabinet Decision No. 173 of 2026 and the repeal of Nos. 106 of 2025 and 64 of 2025
- Ministry of Finance, Accredited and pre-approved e-invoicing service providers (accessed 9 November 2026: 86 providers)
- Ministerial Decision No. 243 of 2025 on the Electronic Invoicing System (2025)
- Ministerial Decision No. 197 of 2026 amending Ministerial Decision No. 243 of 2025 (in force 1 October 2026; published 19 October 2026): tax group exclusion, 14 business days, storage, system failure repeal
- Ministry of Finance, Amendments to e-invoicing regulations to ease the burden on businesses (19 October 2026)
- Ministerial Decision No. 244 of 2025 on the Implementation of the Electronic Invoicing System (2025)
- Ministerial Decision No. 66 of 2026 (May 2026)
- Ministry of Finance, Targeted amendments to e-invoicing decisions (10 May 2026)
- Ministerial Decision No. 168 of 2026 on ASP eligibility and accreditation (in force 1 October 2026; repeals Ministerial Decision No. 64 of 2025)
- UAE Legislation portal, Cabinet Decision No. 173 of 2026 on e-invoicing violations and penalties and its penalty table (Arabic; in force 15 October 2026; read 5 November 2026)
- Cabinet Decision No. 106 of 2025 on e-invoicing violations and penalties (8 December 2025; repealed by Cabinet Decision No. 173 of 2026)
- Ministry of Finance, UAE Electronic Invoicing Guidelines v2.0 (26 October 2026; replaces v1.1 of 1 June 2026)
- Federal Tax Authority, Calls on persons subject to e-invoicing to comply with the legal deadlines (25 October 2026)
- Ministry of Finance, UAE Electronic Invoice Mandatory Fields v1.1 (28 October 2026)
- Ministry of Finance, Considerations for selecting an Accredited Service Provider v1.1 (28 October 2026)
- OpenPeppol, PINT-AE specification 1.0.4 (29 July 2026)
Last reviewed 9 November 2026 against Guidelines v2.0, Mandatory Fields v1.1, the ASP selection considerations v1.1, the Ministerial and Cabinet Decisions and the FTA's 25 October notice; penalties updated to Cabinet Decision No. 173 of 2026 on 5 November 2026. This guide explains published guidance and isn't legal or tax advice.