Guide · Vaping duty stamps
Vaping duty stamps: a goods-in checklist for UK wholesalers
On this page12 sections
Short answer: from 1 October 2026, vaping products released for sale in the UK must carry a 42mm × 18mm vaping duty stamp on the outermost retail pack. As a wholesaler you don't buy or apply stamps. Your job is to check them at goods-in, quarantine anything doubtful, and keep a record of what you checked, because HMRC's penalties are counted per unit and start at £2,500.
Download the blank goods-in log (CSV) to record delivery checks in Excel or Google Sheets. The instructions below explain the fields.
From our side
The question I get most is "do we have to check every single pack?" Nobody wants to open every carton. What we suggest is checking a sample per carton, logging who checked it, and quarantining the batch the moment one looks wrong.
— Avi Singh, Founder
This is the practical companion to our Vaping Products Duty guide for wholesalers, which covers the duty itself and the 31 March 2027 deadline. Here we cover the stamp: what it looks like, how to check it, what your product data should hold, and what happens if you get it wrong.
What is a digital tax stamp?
"Digital tax stamp" is the general name for what HMRC calls a digital vaping duty stamp: the 42mm × 18mm secure label on the outermost retail pack, with a scannable code added. The code lets the product be authenticated and traced through the supply chain. Digital stamps have been available since 1 September 2026, and from 1 January 2027 they are the only kind that can be applied.
What a valid stamp looks like
| Feature | What HMRC says |
|---|---|
| Size and shape | Rectangle, 42mm long × 18mm wide |
| Position | On the outermost retail packaging, fixed so the pack can't be opened without damaging the stamp or the pack |
| Security | Multiple physical security features |
| Digital code | Digital stamps carry a scannable code for authentication and supply-chain tracing |
| Re-use | A stamp can't be re-used once applied |
Stamps come in two kinds during the changeover:
- Transitional stamps have physical security features only and aren't scanned. Approved businesses can buy them until 30 November 2026 and apply them until 31 December 2026.
- Digital stamps have been available since 1 September 2026 and include the scannable code. From 1 January 2027 only digital stamps can be applied.
So between October and the end of March you'll see three kinds of legitimate stock on your shelves: transitional-stamped, digitally stamped, and unstamped stock that was made or imported before 1 October 2026. Your goods-in process has to handle all three.
The goods-in checklist
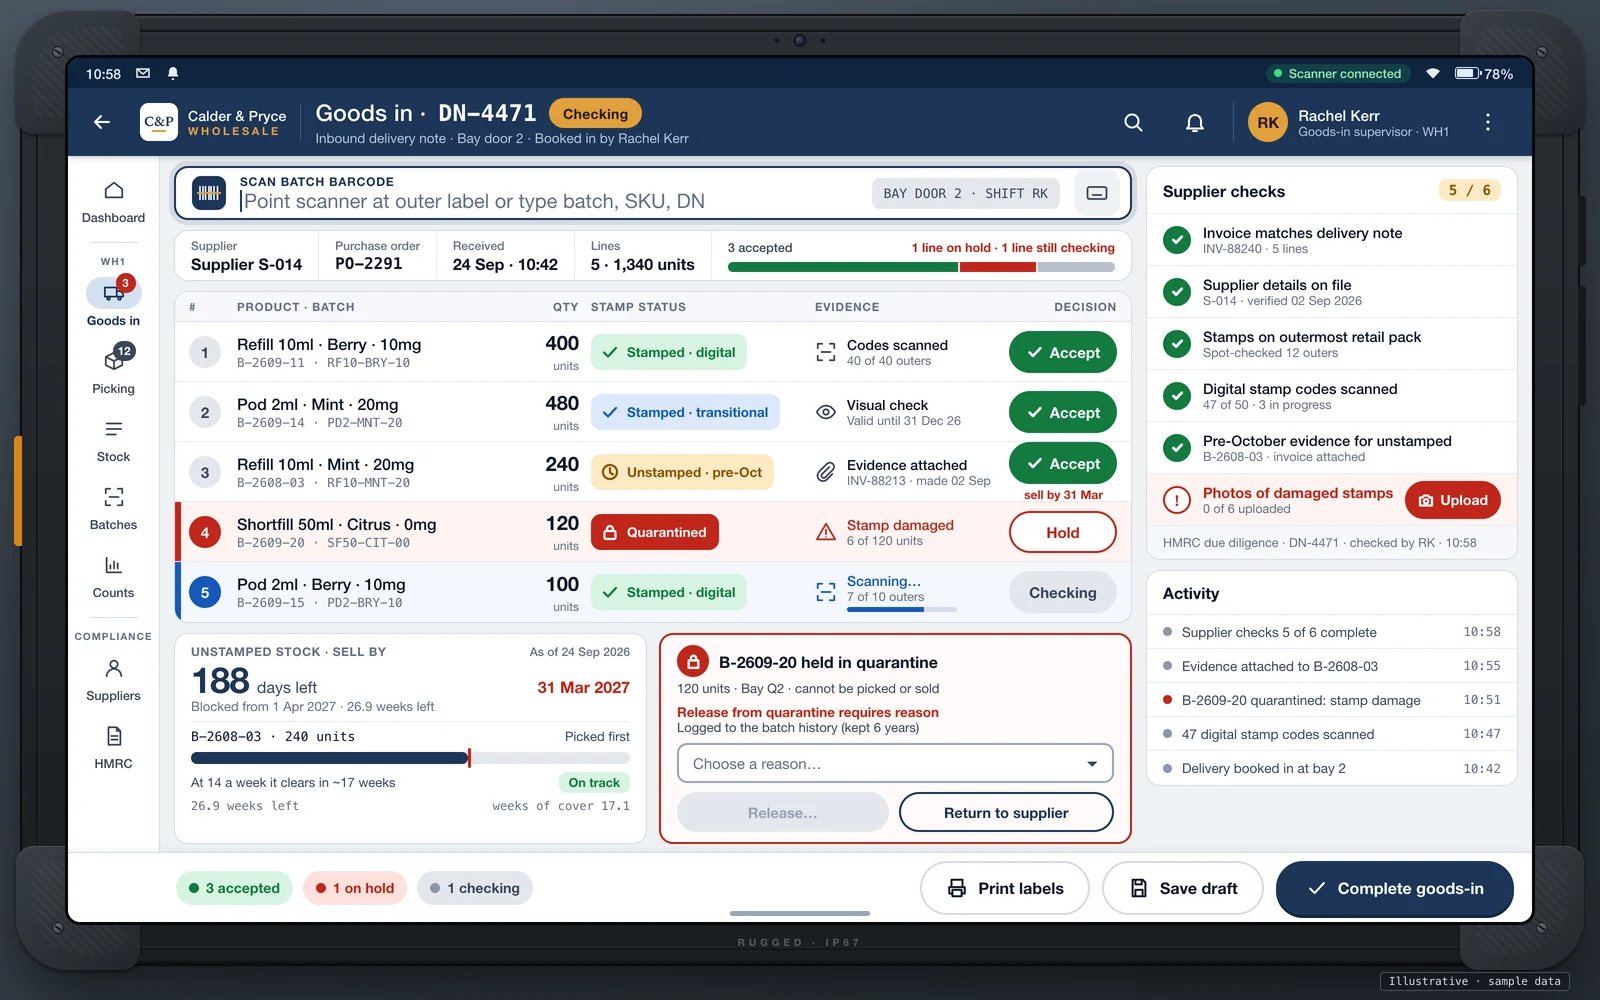
Run this on every delivery of vaping products. It takes a minute per line once staff are used to it.
- Is a stamp needed? Anything produced in or imported into the UK on or after 1 October 2026 needs one. Unstamped stock is only acceptable if you have evidence it was produced or imported before that date.
- Is it on the right packaging? The outermost retail pack, not the shipping carton or the inner blister.
- Does it seal the pack? If the pack can be opened without tearing the stamp, something is wrong.
- Is it intact? Reject stamps that look damaged, altered, re-used, peeled or missing.
- For digital stamps, can it be verified? HMRC says digital stamps support authentication through the supply chain using a scanning app provided by the duty stamp supplier. Its guidance doesn't yet spell out how wholesalers get access, so ask your supplier or HMRC. Until then, rely on the physical checks above and the paperwork.
- Do the paperwork and the supplier check out? Normal invoices and delivery notes, a supplier you can identify, and a clear answer to where the goods came from.
- Record the result against the delivery: stamped, unstamped with evidence, or quarantined.
If anything fails, don't put the stock into sellable inventory. Move it to a quarantine location, ask the supplier for an explanation in writing, and record what you did. HMRC's guidance says that if you can't satisfy yourself the stock is legitimate, you shouldn't buy, supply or sell it. Suspected illicit or counterfeit products can be reported to HMRC or Trading Standards.
Use the goods-in log
Download the goods-in log template (CSV). It is a blank operational worksheet, with no sign-up required.
Use one row per delivery, SKU and batch. Record the supplier and delivery reference, quantity, stamp status, evidence reference, person checking and any action taken. Suggested status labels are digital, transitional, unstamped — evidence to review, and on hold. A status label on its own does not establish whether stock can be sold.
Keep the invoice, delivery note and supporting evidence alongside the log; put their file references in the evidence column. If a batch needs review, record the reason and who authorised any later release. The worksheet helps organise your checks; it is not an HMRC stamp-authentication tool or a substitute for the checks in HMRC's guidance.
If you run a shop: what retailers check
Most of this page applies to vape shops too. HMRC says a business that only sells duty-paid vaping products, wholesale or retail, doesn't need approval for Vaping Products Duty or the stamps scheme, and can't buy stamps. What HMRC's internal manual expects of wholesalers and retailers (VPDS171800) is:
- purchase and sales records showing supplier, date, SKU, volume and whether a stamp was on the retail pack
- due-diligence checks on suppliers, and evidence that products offered for sale after 1 April 2027 are legitimately stamped
- a record of any seizures or suspected counterfeit or faulty stamps, and what you did
A shop's goods-in check is the same seven steps as above, just on smaller deliveries. From 29 October 2026 shops also have the new age-of-sale and promotion rules; our Tobacco and Vapes Act summary covers those.
The product data your system should hold
Manufacturers and importers have to register each product's details in the stamp supplier's system. Mirroring the same fields in your own product master makes goods-in checks and HMRC questions far easier, because your records describe products the same way HMRC's system does:
| Field | Notes |
|---|---|
| Product name and description | As sold |
| GTIN / barcode | The 1D barcode for the SKU |
| Liquid volume | In ml, to the nearest 0.1ml (also drives the £2.20 per 10ml duty) |
| Brand and flavour | As on the pack |
| Product type | Prefilled pod, prefilled device, bottle or other |
| Nicotine content | mg/ml |
| ECID or GBID | The notification ID, required where nicotine is above 0mg/ml (how to check it on the MHRA list) |
| Stamp status per batch | Stamped (transitional or digital), unstamped with evidence, quarantined |
If your products live in a spreadsheet with a name and a price, adding these columns now is the single most useful thing you can do while the first stamped deliveries are arriving. They're all part of the product record in the portals we build.
HMRC's penalties for unstamped products
From 1 October 2026 HMRC can charge a penalty if you sell, offer for sale or deal in unstamped vaping products packaged for retail sale where a stamp is required. The amount depends on how many retail units are found and how many times you've failed in the previous 24 months:
| Units found | First time | Second time | Three or more times |
|---|---|---|---|
| Fewer than 100 | £2,500 | £5,000 | £7,500 |
| 100 to 299 | £5,000 | £7,500 | £10,000 |
| 300 to 499 | £7,500 | £10,000 | £10,000 |
| 500 or more | £10,000 | £10,000 | £10,000 |
On top of the penalty:
- Seizure: products and stamps can be forfeited, and HMRC says it may also remove lawful vaping products found on the premises at the same time.
- Prosecution: in the most serious cases, an unlimited fine, up to two years in prison, or both.
The practical lesson is that one mixed pallet can cost more than the stock is worth. Keeping quarantined and unstamped stock physically and digitally separate from stamped stock is cheap insurance.
What changes on 1 April 2027
The grace period for pre-October unstamped stock ends on 31 March 2027. From 1 April 2027 every vaping product outside duty suspension must carry a valid stamp, and you must not hold or sell unstamped products. Plan the run-down now: the duty guide shows a simple weeks-of-cover check.
How we build this into a portal
Our trade portal already handles sales and warehousing for one UK vape wholesaler. Stamp-status controls, quarantine approvals and deadline-based stock blocks are capabilities we can build for your operation; they are scoped for your project rather than presented here as features already running at that client.
For a useful first discussion, tell us:
- how many warehouses receive deliveries;
- roughly how many SKUs and batches you handle;
- which stock or accounting system you use;
- how you currently record supplier evidence and release held stock.
See our UK vape wholesale software page for the wider ordering and warehouse scope, or B2B ordering portal for trade accounts and orders. We agree a fixed quote after a walkthrough and fit check.
Discuss your goods-in workflow and get a quote.
Related guides
- Vaping Products Duty guide for wholesalers: the duty itself and the 31 March 2027 deadline
- Running down unstamped vape stock
- MHRA notified products list: how to check a vape line
- Vape duty calculator
- Vape retail licensing in the UK
Sources
- HMRC, How vaping duty stamps work (updated 26 August 2026; unchanged on 28 October 2026)
- HMRC, Vaping duty stamps: penalties and sanctions (CC/FS87) (published 23 April 2026; unchanged on 28 October 2026)
- HMRC, Handling wholesale or retail vaping products in the UK (updated 7 October 2026)
- HMRC internal manual, VPDS171800: Record keeping: wholesalers and retailers
- HMRC, One month until Vaping Products Duty and the Vaping Duty Stamps Scheme start
Last reviewed 29 October 2026: every stamp, date and penalty re-checked against the HMRC pages above, plus a digital tax stamp definition and a section for retailers. Goods-in worksheet added 12 October 2026. This guide summarises HMRC's published guidance for wholesalers. It isn't legal or tax advice.