Guide · UAE VAT invoices
UAE tax invoice requirements: full vs simplified invoices, credit notes and e-invoicing
On this page12 sections
Short answer: a UAE-registered business must issue a full tax invoice with 12 required particulars within 14 days of the supply. A simplified tax invoice with five particulars is allowed when the customer isn't VAT-registered, or is registered and the supply is AED 10,000 or less. Amounts are shown in AED at the Central Bank rate. Once your business is in the e-invoicing system, the simplified-invoice route stops for the invoices you send as e-invoices, which means your business customers.
From our side
The thing I see most on invoices from older billing systems is the credit note. Invoices are usually fine. Credit notes get made by editing the old invoice or not issued at all, and that's exactly what e-invoicing will catch.
— Avi Singh, Founder
These UAE tax invoice requirements come from the VAT Decree-Law and Articles 59 and 60 of the VAT Executive Regulation, as published by the Federal Tax Authority with amendments up to Cabinet Decision No. 149 of 2026. The standard VAT rate is 5%.
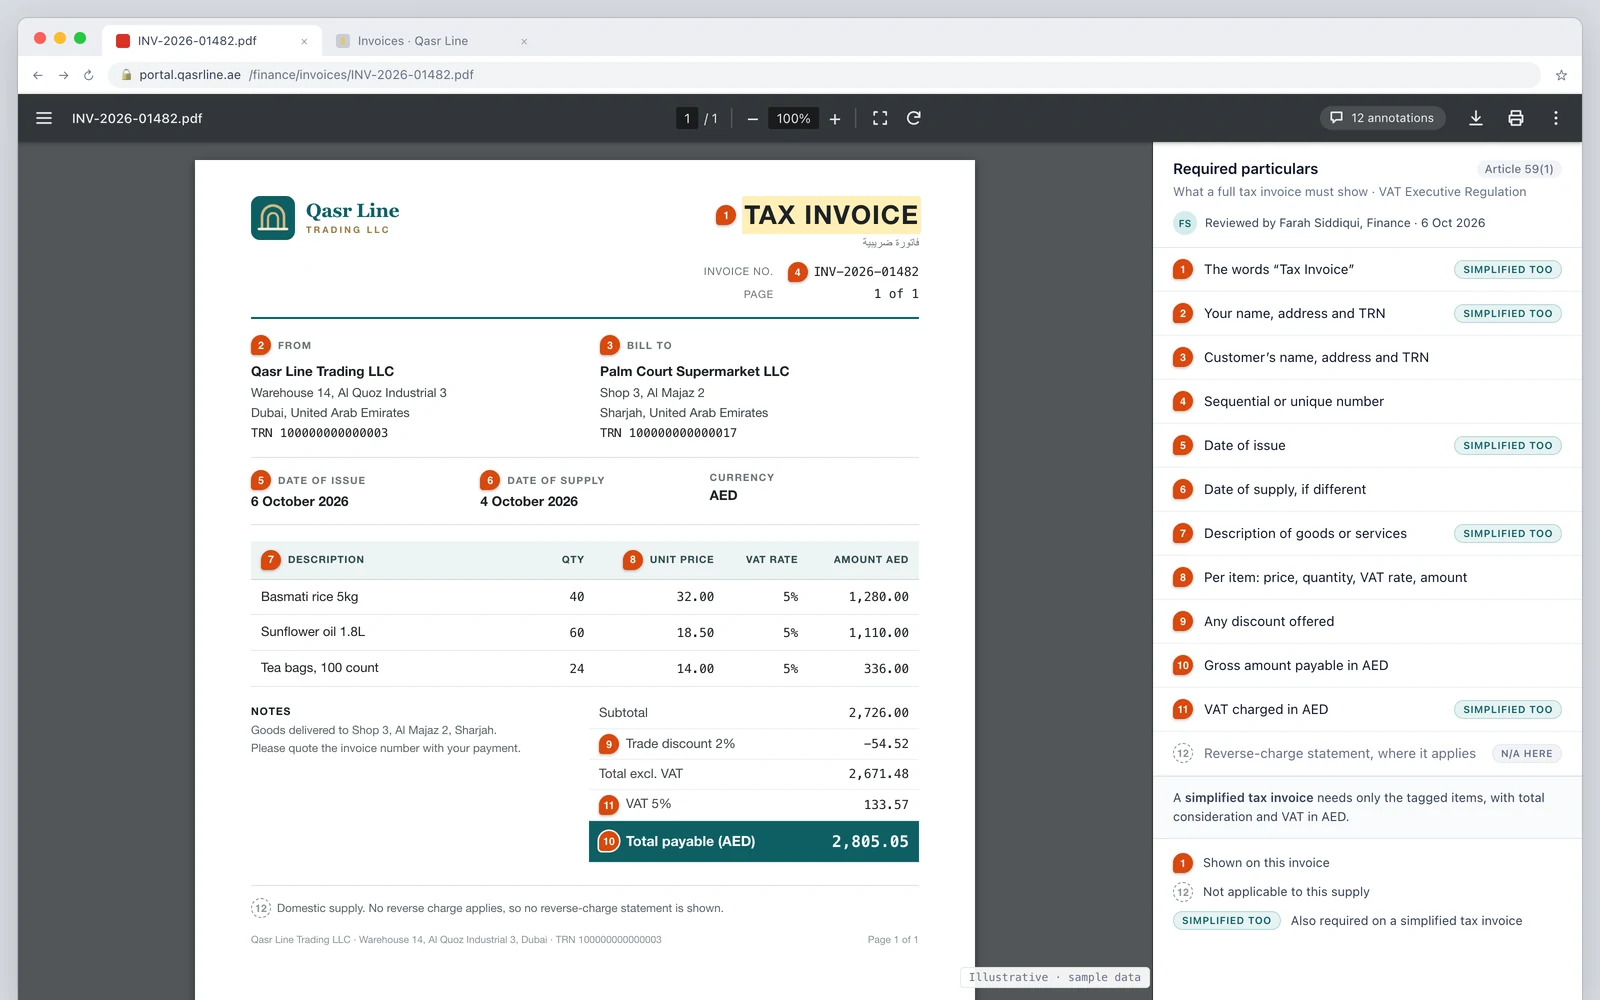
Full vs simplified tax invoice: what each must show
| Particular | Full tax invoice | Simplified tax invoice |
|---|---|---|
| The words "Tax Invoice" clearly displayed | Yes | Yes |
| Your name, address and TRN | Yes | Yes |
| Customer's name, address and TRN (if the customer is registered) | Yes | No |
| Sequential or unique invoice number | Yes | No |
| Date of issue | Yes | Yes |
| Date of supply, if different from the issue date | Yes | No |
| Description of goods or services | Yes | Yes |
| Per item: unit price, quantity, VAT rate and amount payable in AED | Yes | No |
| Any discount offered | Yes | No |
| Gross amount payable in AED | Yes | No |
| VAT charged in AED, with the exchange rate if converted | Yes | Total consideration and VAT in AED only |
| Reverse-charge statement and legal reference, where the customer accounts for VAT | Yes | Not allowed for reverse-charge supplies |
Source: Article 59(1) and 59(2) of the VAT Executive Regulation. The regulation doesn't require a number on a simplified invoice, but give it one anyway so your system can trace it in your records and returns.
When a simplified tax invoice is allowed
Article 59(5) allows a simplified tax invoice in two cases, and never where the reverse charge applies:
- The customer isn't a VAT registrant, whatever the amount.
- The customer is a registrant and the consideration for the supply doesn't exceed AED 10,000.
For a billing system, that's one rule to build: check the customer's registration status and the invoice total before choosing the layout, and fall back to the full invoice when in doubt. A full invoice is always acceptable where a simplified one is allowed; the reverse isn't true.
When to issue a tax invoice
| Document | Deadline | Source |
|---|---|---|
| Full tax invoice | Within 14 days of the date of supply | VAT Decree-Law Art. 67; Exec. Reg. Art. 59(13) |
| Simplified tax invoice | On the date of supply | Exec. Reg. Art. 59(13)(a) |
| Summary tax invoice (several supplies to one customer) | Within 14 days of the end of the calendar month of supply | Exec. Reg. Art. 59(13)(b) |
| Tax credit note | Within 14 days of the event that reduces output tax | VAT Decree-Law Art. 62(2) |
If you issue a summary tax invoice, you must not also issue separate tax invoices for the supplies it covers (Article 59(6)).
Currency and language
You can invoice in any currency, but Article 69 of the VAT Decree-Law requires the tax invoice amounts to be converted to AED at the Central Bank of the UAE exchange rate on the date of supply. A full invoice shows the VAT in AED and the rate applied. Store the rate with the invoice so the figures can be reproduced later.
Articles 59 and 60 don't prescribe a language for the invoice itself. If you issue only in English, ask your tax adviser whether the FTA could require Arabic translations of your records. The e-invoicing format supports both Arabic and English.
Tax credit notes
A tax credit note corrects output tax downwards. Article 61 of the VAT Decree-Law lists the events: the supply was cancelled, the tax treatment changed, the agreed price changed, goods were returned and the consideration refunded, or tax was charged or applied in error. Article 62(2) then requires the credit note within 14 days of the event.
Article 60(1) of the Executive Regulation sets its contents:
| Particular | Required |
|---|---|
| The words "Tax Credit Note" clearly displayed | Yes |
| Your name, address and TRN | Yes |
| Customer's name, address and TRN (if registered) | Yes |
| Date of issue | Yes |
| Value on the original invoice, correct value, the difference, and the VAT on the difference, in AED | Yes |
| Short explanation of why it was issued | Yes |
| Enough information to identify the original supply | Yes |
If you issue more than one credit note against the same invoice, each later note starts from the value as already adjusted. A VAT-registered buyer can raise a credit note on your behalf if you both agree you won't issue one, and it must be marked "Tax Credit Note created by buyer".
Other rules your system should handle
- Self-billing: a VAT-registered customer may raise the invoice for you if you both agree in writing that you won't issue one. It must say "Tax Invoice raised by buyer".
- Agents: a registered agent can issue the invoice for a principal, and both keep records of each other's name, address and TRN.
- Electronic invoices today: tax invoices and credit notes can be issued by electronic means if you can store them securely and guarantee their origin and integrity. A PDF by email works under this rule until e-invoicing applies to you.
What changes once you're on e-invoicing
When you must, or choose to, issue tax invoices as e-invoices, Article 59(16) switches off Clauses 2, 3, 5, 7, 8 and 15 of Article 59. In practice:
- No simplified tax invoices for the invoices you send as e-invoices. B2B and B2G sales need the full structured invoice, including sales under AED 10,000.
- No "wholly zero-rated, no invoice" relief and no FTA waivers of particulars under the old clauses.
- The paper-and-PDF conditions no longer govern those invoices; the e-invoice is the tax invoice.
- Credit notes follow suit. Article 60(8) disapplies the value-difference line and the waiver and electronic-means clauses of Article 60 for e-credit notes.
- A 14-business-day clock, with a VAT carve-out. Since 1 October 2026, Article 6(5) of Ministerial Decision No. 243 of 2025, as replaced by Ministerial Decision No. 197 of 2026, says e-invoices and e-credit notes must be issued and transmitted within 14 business days of the Date of Business Transaction, which the Decision defines as the earlier of the day the transaction occurred and the day payment was received. But that clause is expressly "subject to" Article 6(4), which says an issuer who is VAT-registered must issue and transmit within the timeline in the VAT Law. Our reading: for a VAT-registered business the VAT clocks above (14 calendar days) are the ones to build to, because the e-invoice is the tax invoice. Check with your adviser if you are not VAT-registered.
- FTA waivers don't carry over. The MoF's e-invoicing guidelines (version 2.0, 26 October 2026, section 7) say administrative exceptions the FTA grants for tax invoices and credit notes don't apply to e-invoices and e-credit notes.
- VAT groups get longer. Ministerial Decision No. 197 of 2026 lists transactions between members of the same tax group among the excluded transactions for 24 months from 1 January 2027; the guidelines (section 6.3.2.1) call it a grace period that affects timing only. Invoices to customers outside the group are not covered.
Consumer (B2C) sales are outside e-invoicing: the MoF's guidelines (section 6.2) say there is no obligation to issue an e-invoice for a supply made to a consumer. So our reading is that Article 59(16) isn't triggered for those invoices and simplified invoices remain available for sales to consumers. Confirm that with your adviser for your own sales mix. For a business customer that hasn't implemented e-invoicing yet, section 10.2 says a regular tax invoice (a PDF, for example) is required in addition to the e-invoice, and the e-invoice carries the predefined endpoint 0235:9900000098 in place of their Peppol ID. Their onboarding status doesn't change your obligation to issue the e-invoice (section 6.1). The dates, the 51 mandatory fields and how to connect your system to an Accredited Service Provider are covered in our guide to ERP integration for UAE e-invoicing.
Status today (9 November 2026)
- The deadline for businesses with revenue of AED 50 million or more to appoint an ASP was 30 October 2026 (Ministerial Decision No. 66 of 2026; the Federal Tax Authority repeated the date in its 25 October 2026 notice). The phase table in the guidelines v2.0 prints 31 October. Either way it has passed; go-live for that group stays 1 January 2027.
- We found no extension or grace period announced since: the Ministry's eInvoicing page (last updated 9 November 2026) and its latest news items show none. This is a check on that date, not a promise that nothing will change.
- The Ministry's list of Accredited Service Providers had 86 entries on 9 November 2026.
How long to keep invoices
The MoF's e-invoicing guidelines (version 2.0, 26 October 2026, section 5.4), citing Article 3(1) of the Tax Procedures Executive Regulation, set the retention periods:
| Who | Keep records for |
|---|---|
| Taxable persons | 5 years following the tax period the records relate to |
| Other persons | 5 years from the end of the calendar year the document was created |
| Real estate records | 7 years from the end of the calendar year the document was created |
| Taxable persons: during a dispute or tax audit, or after an audit notice | 4 more years |
| Voluntary disclosure made in the fifth year after the tax period | 1 more year from the disclosure |
For e-invoices, Article 11 of Ministerial Decision No. 243 of 2025 was replaced from 1 October 2026. The original text required e-invoice data to be stored "within the State"; the new text drops that phrase and requires e-invoices, e-credit notes and associated data to be kept for the Tax Procedures Law period and to be capable of being produced on request. The guidelines (section 5.4) treat that as met when the records are kept in a system that preserves their integrity, can be provided to the FTA promptly, and can be reproduced complete and readable. Check any hosting contract against those three tests. Your ASP may store the records for you if the contract says so, but the legal duty stays with you (appendix 4), and the guidelines don't require storage at any particular layer of the system.
A tax invoice checklist for your billing system
Use this to test the invoice templates in your billing app, ERP or ordering portal:
- Does every invoice print "Tax Invoice", and every credit note "Tax Credit Note"?
- Is your 15-digit TRN on every invoice, and the customer's TRN where they're registered?
- Does every invoice have its own number, in a sequence or at least unique (Article 59(1)(d) accepts either), with corrections made by credit note, not by deleting or reusing numbers?
- Does the system choose simplified or full layout from the customer's status and the AED 10,000 limit, and block simplified invoices for reverse-charge supplies?
- Are VAT and totals shown in AED, with the exchange rate, on foreign-currency invoices?
- Is the supply date printed when it differs from the issue date?
- Does each credit note reference the original invoice, show the original and corrected values, and give a reason?
- Can you find every invoice and credit note for the full retention period?
- Is there a switch for the day you move to e-invoicing, when simplified invoices stop for business customers?
How we help
We build and change billing systems, ERPs and trade ordering portals for businesses in the UAE and elsewhere, working remotely. We don't have a UAE office and we don't give tax advice. We make invoice and credit-note templates carry the right particulars, add the full-or-simplified logic, store AED amounts and exchange rates, and prepare the same system to produce e-invoice data for the Accredited Service Provider you choose. You get a fixed quote after a 20-minute call. Book a call or see what we build for UAE businesses.
Sources
- Federal Tax Authority, Federal Decree-Law No. 8 of 2017 on VAT and amendments (published 28 November 2025; Articles 61, 62, 67, 69)
- Federal Tax Authority, VAT Executive Regulation (Cabinet Decision No. 52 of 2017) and amendments (to Cabinet Decision No. 149 of 2026; Articles 59 and 60)
- Federal Tax Authority, VAT legislation (accessed 9 November 2026; the Executive Regulation listed is the September 2026 consolidation cited above)
- Ministry of Finance, UAE Electronic Invoicing Guidelines v2.0 (26 October 2026; sections 5.4, 6.1, 6.2, 6.3.2.1, 7, 8.3, 10.2 and appendix 4)
- Ministerial Decision No. 243 of 2025 on the Electronic Invoicing System (2025; original Articles 11 and 12)
- Ministerial Decision No. 197 of 2026 amending Ministerial Decision No. 243 of 2025 (in force 1 October 2026; Articles 4, 6(5) and 11 replaced, Article 12 repealed)
- Ministerial Decision No. 66 of 2026 amending Ministerial Decision No. 244 of 2025 (appointment deadline 30 October 2026)
- Federal Tax Authority, news of 25 October 2026 on e-invoicing deadlines
- Ministry of Finance, eInvoicing programme hub and list of Accredited Service Providers (both accessed 9 November 2026)
Last reviewed 9 November 2026: every particular, deadline and retention period re-checked against the Decree-Law, the Executive Regulation (to Cabinet Decision No. 149 of 2026), Ministerial Decisions No. 243, 66 and 197 and the MoF's e-invoicing guidelines v2.0. This guide explains published guidance and isn't legal or tax advice.